
BIX ARTICLE
Foreign buying lifts bond holdings by RM7.2bil to RM325.5bil
Nov 11, 2026
|
3 min read
Featured Posts
Social Bonds Illustrative Use-Of-Proceeds Case Studies Coronavirus
Jul 06, 2020
|
2 min read
Sustainable Banking Network (SBN) Creating Green Bond Markets
Jul 06, 2020
|
2 min read
Why is Inflation Making a Big Comeback After Being Absent for Decades in the U.S.?
Mar 24, 2022
|
7 min read
SC issues Corporate Governance Strategic Priorities 2021-2023
Mar 29, 2022
|
3 min read
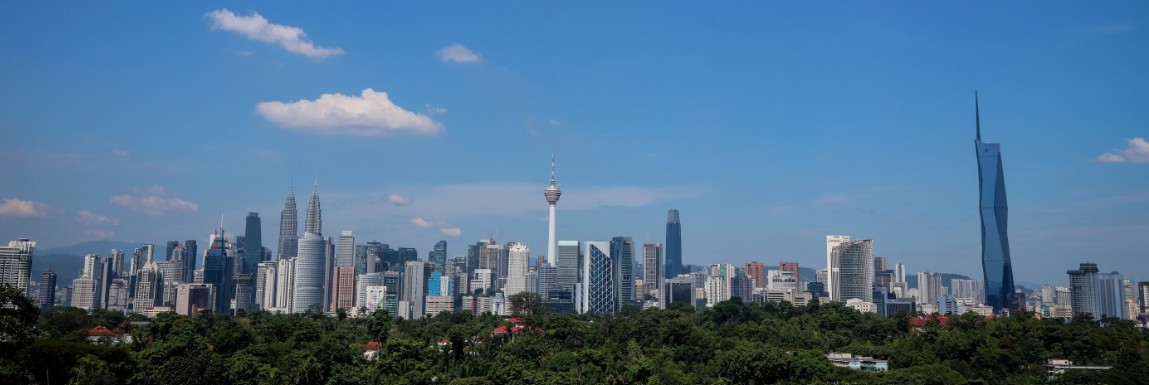
KUALA LUMPUR: Foreign holdings of Malaysian bonds posted a strong inflow in October, signalling confidence in Malaysia's economic fundamentals.
In its October fixed income review, MBSB Research said the outstanding value moved higher by RM7.2 billion to RM325.5 billion.
"Foreign holdings saw a significant increase in the final week of October, reaching a record high.
"We estimate that the share of foreign holdings in total outstanding government debt edged higher to 21 per cent," it said.
The firm said the US Treasury (UST) yield curve experienced a flattening last month, averaging around 5.12 per cent on the back of heightened geopolitical risk and expectations for a delayed rate hike.
In early October, a sharp sell-off temporarily pushed the 10-year UST yield to a multi-decade high of 5.342 per cent.
However, yields steadily eased lower through the remainder of the month.
Downward momentum accelerated following the announcement made by the Federal Open Market Committee (FOMC) announcement, where it voted 10–2 to hold the fed funds target rate steady at 3.75 per cent–4.00 per cent.
"The split decision signalled a hawkish hold, reinforcing the possibility of further monetary tightening, although the US Federal Reserve (Fed) opted to assess incoming economic data before its next policy decision.
"Nevertheless, market expectations remain tilted toward a potential 25 basis points (bps) rate hike at the upcoming FOMC meeting in December," said the firm.
Back home, the Malaysian government securities (MGS) yield curve closed lower last month, across all tenors, as most of the decline was towards the longer end of the curve, indicating a bull flattening of the yield curve.
The yield curve initially declined during the early part of the month, but later closed relatively higher, broadly tracking the movement of the UST yields.
The MGS 10-year yield traded between 3.799 per cent and 4.028 per cent last month, while the UST 10-year yield traded lower within the range of 4.930 per cent to 5.307 per cent.
"Concurrently, we expect the continuous hawkish outlook for the US fed funds rate has led markets to price in a hawkish and 'higher-for-longer' policy stance.
"Investors anticipate a 25bps rate hike at the upcoming FOMC meeting in December.
"On that note, we expect MGS yields will continue to mirror the movement in UST yields in the short- to medium-term, subject to inflationary risk and the Middle East conflicts, on top of the possibility of a further rate hike by the FOMC."
Source: Foreign buying lifts bond holdings by RM7.2bil to RM325.5bil (November 10, 2026 @ 7:10pm) www.nst.com.my. Retrieved from https://www.nst.com.my/business/corporate/2026/11/1574882/foreign-buying-lifts-bond-holdings-rm72bil-rm3255bil
Disclaimer
The information provided in this report is of a general nature and has been prepared for information purposes only. It is not intended to constitute research or as advice for any investor. The information in this report is not and should not be construed or considered as an offer, recommendation or solicitation for investments. Investors are advised to make their own independent evaluation of the information contained in this report, consider their own individual investment objectives, financial situation and particular needs and should seek appropriate personalised financial advice from a qualified professional to suit individual circumstances and risk profile. The information contained in this report is prepared from data believed to be correct and reliable at the time of issuance of this report. While every effort is made to ensure the information is up-to-date and correct, Bond and Sukuk Information Platform Sdn Bhd (“the Company”) does not make any guarantee, representation or warranty, express or implied, as to the adequacy, accuracy, completeness, reliability or fairness of any such information contained in this report and accordingly, neither the Company nor any of its affiliates nor its related persons shall not be liable in any manner whatsoever for any consequences (including but not limited to any direct, indirect or consequential losses, loss of profits and damages) of any reliance thereon or usage thereof.
YOU MAY ALSO LIKE
ARTICLE
Nov 12, 2026
|
3 min read
ARTICLE
Nov 11, 2026
|
5 min read
ARTICLE
Nov 11, 2026
|
3 min read
ARTICLE
Nov 11, 2026
|
2 min read